Brace for a Slowdown in 2012
While fears of a double-dip recession are easing, GDP and industrial production numbers suggest 2012 will not be as robust as 2011. As recently as June, economists were predicting growth of 3 to 3.5 percent for 2012, but new consensus forecasts are calling for growth of just 2 to 2.5 percent. That one percentage point drop means we may need about 20,000 fewer new trucks this year
Truck production in 2012 could be lower than predicted because of downward revisions in GDP forecasts.
While fears of a double-dip recession are easing, GDP and industrial production numbers suggest 2012 will not be as robust as 2011. As recently as June, economists were predicting growth of 3 to 3.5 percent for 2012, but new consensus forecasts are calling for growth of just 2 to 2.5 percent. That one percentage point drop means we may need about 20,000 fewer new trucks this year.
Speaking at Heavy Duty Dialog last week in Las Vegas, part of the proceedings at heavy Duty Aftermarket Week, economist, Eli Lustgarten, Senior vice president at Longbow Securities, predicted that 2012 would be a healthy year overall -- and on par with previous post-recession recovery periods -- but he cautioned that we will not witness the same performance we saw last year.
"The economic climate here was great for a recovery in 2011. We had very strong productivity coming out of the recession, and negative labor costs. It was a perfect combination for productivity," he says. "Company's margins were spectacular coming back from 2009 and we saw great profits, but we're starting to come out of that cycle in 2012."
Lustgarten calls it the Bullwhip Effect.
During the downturn, people just cut everything back and shut down, he says. Inventory dropped to unimaginable levels and mathematically, about $180 billion in inventory disappeared from the system. Coming out the other side, there was a rebalancing and restocking of the supply chain, which produced a significant improvement in economic performance compared to 2009, but in 2010, manufacturing output remained about 30 percent below pre-recession levels.
In 2011, inventory levels in many sectors started rising to levels commensurate with the economic climate, but not back to where they were 24 to 30 months prior.
"That was still a huge swing, and we saw a huge change in production and that produced a huge change in inventory levels," Lustgarten pointed out. "In 2012, we'll be looking for the new normal. But that level will be below where we came from in the 2006 to 2008 period when new home construction peaked, along with automotive, heavy truck and construction equipment manufacturing.
Manufacturing was very strong in 2010, and while the industrial sector was one of the leading drivers in the U.S. recovery, consumer and business confidence levels remained weak, and tight credit continued to hamper growth in the small business sector. Slow housing and commercial construction growth stymied the recovery of the construction sector.
But while manufacturing is important, what really counts is the way GDP affects the industrial economy, he said. "Industrial production is a key driver of the industrial economy and the manufacturing side, and they are key drivers for the truck market."
Lustgarten says 2011 came in just under 2 percent GDP growth, and as recently as six months ago, economists were predicting growth of between 3 to 3.5 percent for 2012. It now appears those numbers were a little optimistic. The consensus forecast for 2012 is now in the 2 to 2.5 percent range. For truck fleets, that one percentage point spread is significant -- as it is for truck manufacturing.
If you believe GDP is running at 2 to 2.5 percent, you're going to believe industrial production is also going to be in the mid-twos. If you believe the economy is going to run at 3 to 3.5 percent, then industrial production is going to be 3.5 to 4 percent. What's the difference?
"At about 2.5 percent growth in industrial production, truck fleets are stabilized. You buy for replacement, but you really don't expand the fleet," says Lustgarten. "When you get to 3.5 to 4 percent GDP and industrial production numbers, you begin to expand fleets."
In real terms, a small swing in GDP or industrial production is going to create significant swings in estimated demand, and that will create significant variations in build rates.
Towards the end of 2011, Q4 build rates accelerated, and that growth seemed to be driven by a quiet pre-buy of fleets looking a cashing in on a depreciation credit that expired at the end of the year, and by fears of price hikes in 2012. The extent to which that skewed the demand/production numbers was not great, but Lustgarten says.
"There was clear evidence of a surge in heavy truck demand in December, with final production estimates for 2011 expected to be 255,000 units," he notes.
Based on 2011 production numbers and Q4 numbers in particular, with new estimates on the 2012 GDP growth revised downward to 2 to 2-5 percent from 3 to 3.5 percent, recent truck production estimates could off by as many as 20,000 units, Lustgarten said.
If GDP for 2012 can be sustained at 3 percent, we could see as many as 300,000 Class 8 trucks roll of assembly lines this year. However, if GDP grows at a rate of only 2 percent, estimated production could fall to 280,000.
"That means a lot of orders could be cancelled, opening up a lot of build slots in 2012. The bottom line is this: we're leveling out, and it's going to be tough to hold production at current levels. That's the impact of going from 3 percent to 2 percent GDP growth."
More Fleet Management
ITS Logistics Settles Religious Harassment Case
The Nevada-based logistics firm agreed to pay more than $396,000 to settle a religious harassment charge involving an employee's Jewish identity.
Read More →
Your Trucks Are Busy. That Doesn’t Mean They’re Winning.
High utilization doesn’t always mean strong margins. Looking beyond the current load can help fleets make better dispatch decisions and get more value from each truck’s time.
Read More →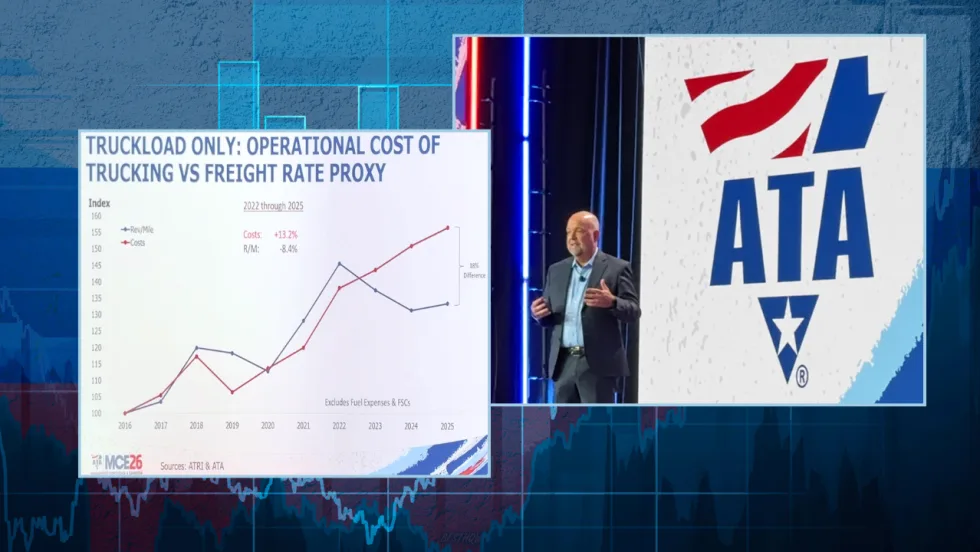
Why This Trucking Recovery Is Different
Freight demand remains sluggish, but rising costs and tougher enforcement have taken enough capacity out of the market to change the outlook for motor carriers.
Read More →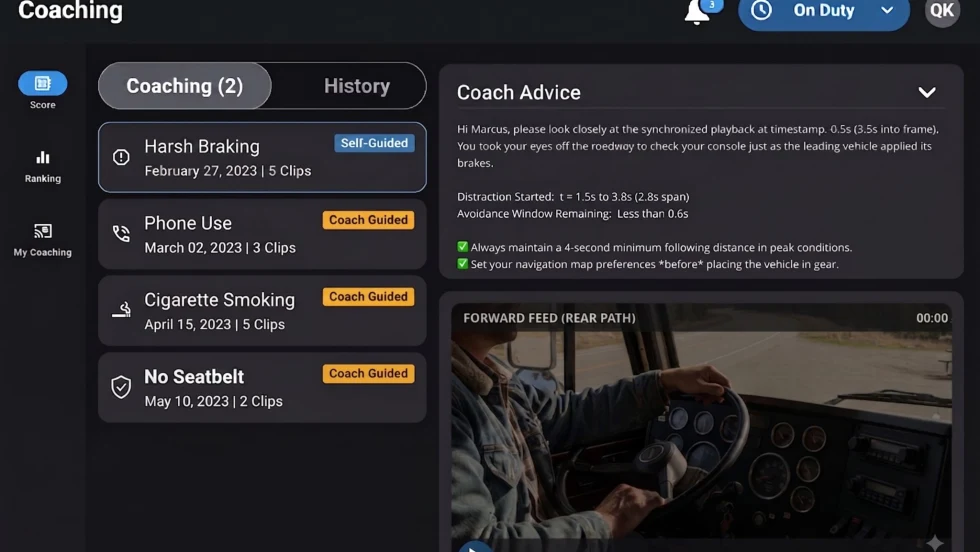
Platform Science Adds Dispatch and Safety Tools
Four additions to PS Fleet help fleets monitor loads, manage driver coaching, share truck locations and adjust video system settings.
Read More →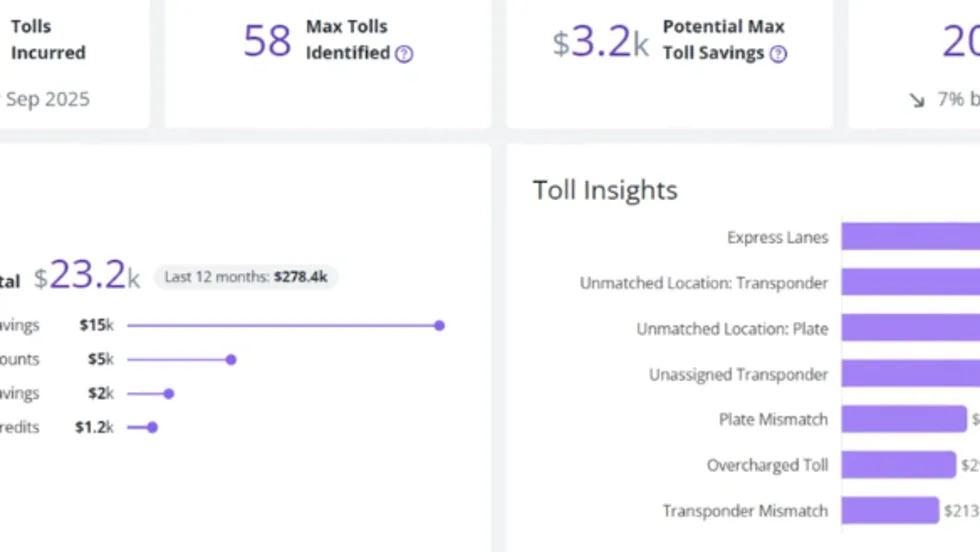
PrePass Intelligence Mines Fleet Bypass, Toll and Safety Data
PrePass Intelligence helps fleets measure bypass savings, flag potential toll overcharges, and spot suspicious transactions by combining data from separate systems.
Read More →
Motive Adds AI Agents for Fleet Operations
New tools automate follow-up on fleet data, from maintenance work orders to driver alerts, with two-way voice conversations planned for later this year.
Read More →
Can You Beat Our Trucking Trivia Challenge?
Test your truck knowledge with 19 trivia questions from Heavy Duty Trucking Exchange. Can you keep up with the fleet pros?
Read More →
BeyondTrucks Adds Rules Checks to Dispatch
New Compatibility Engine checks driver qualifications, equipment requirements and fleet policies before loads are dispatched.
Read More →
Diesel Prices Hijack Trucking’s Worry List
ATRI’s annual survey finds cautious optimism about freight, but diesel costs, litigation, and insurance continue to squeeze fleets. Drivers have different priorities on several issues.
Read More →
Nomination Deadline Extended for HDT Emerging Leaders
Just a few more days to nominate accomplished trucking fleet professionals under 40 who are making an impact and helping lead the industry forward for the HDT Emerging Leaders award. Deadline extended to October 20!
Read More →