
What Railroad Statistics Can Tell Us About Truck Freight Volumes
Is a broad statistic that can give us a real-time second-level read on the magnitude and direction of freight trends? The answer is rail carloads, Jeff Kauffman says.
 MENU
 SEARCH
While some have predicted a cliff-event drop in spot rates like in 2018, there is evidence that we may instead see more of a contract rate extended plateau, similar to what we saw in 2011-2012, Jeff Kauffman suggests.

If the economy grows at about a 5-6% rate this year, and at a 3% rate next year, there is likely to still be support for rate growth in 2022, Kauffman says.
Source: Truckstop.com, FTR
While some industry pundits have predicted a cliff-event drop in spot rates like we saw in 2018, we are getting increasing anecdotal evidence that what we may instead see is more of a contract rate extended plateau, similar to what we saw in 2011-2012.
This is an outcome that neither investors nor fleet executives seem to include in their forecasts, as share prices of truckload companies are under pressure in the stock market, despite better than expected first quarter earnings results. But it’s one that is looking more and more likely.
Many individuals tend to see things through the lens of recent experience – in this case, 2018. The last time spot rates crossed the 20% year-over-year increase level and truck orders surpassed 300,000 units, it was followed by a two-year drought in rates and volumes, caused by the industrial recession of 2019 and the Covid recession of 2020.
However, that environment bears little resemblance to the current situation. 2018 marked the end of a three-year period of prosperity and an overbuild of inventory that lost steam in the fall of 2018.
In the current environment, we have yet to cross into positive territory in two key growth metrics – industrial production (still negative) and growth in business inventories (still negative). Rather, given inventory shortages, a modest re-opening of the economy, and ISM (Institute for Supply Management) manufacturing index readings in the 60+ range (implying high future growth expectations), the economy may be at the front end of an 18- to 24-month growth cusp.
Charting meaningful growth rates will be difficult over the next four to five months, given we are now comparing against last year’s Covid-related global economics closure. Sequential growth analysis may be more helpful. On that basis, using rail carloads as a proxy, we are only recently approaching volume levels that we saw back in January. Rail carloads are clocking +25% year-over-year in the most recent week, but based on our sequential analysis, we are only back to levels where we began the year.
So far this year, three truckload divisions have reported first-quarter earnings (Marten, J.B. Hunt and Knight-Swift). The net capacity increase remains negative. Why so? Although carriers are seeing higher rates now (Knight-Swift reported 16% higher revenue per mile), that has only been the case recently. With extended unemployment benefits delaying new hires, truck driver training schools running at limited capacity, and the national Drug and Alcohol Clearinghouse taking 4,000-5,000 drivers per month out of the truck driver population, growth will be difficult at any reasonable price – no matter how many trucks OEMs produce.
Furthermore, we are hearing anecdotal stories of desperate shippers, unable to effectively use rail or airfreight networks, turning to truck networks to move goods we typically don’t see in longer haul truck routes – scrap metal, pharmaceuticals, and hot-shot cross country moves in lieu of backed-up intermodal. Volumes are increasing, not decreasing. Without additional air cargo capacity or a more fluid rail system with less port congestion, there doesn’t appear to be a catalyst to balance the market in at least the next three to six months.
This leads us to our final point. With limited ability to get goods to where they are going on a timely basis, and new constraints on production of goods related to semiconductor chip shortages, inventories are unlikely to be rebuilt as quickly as originally thought.
In addition, we are beginning to hear increasing anecdotes that shippers may look to try to overbuild product inventory ahead of the holiday and winter season, just in case there’s another healthcare-related slowdown.
When we add all of this up, it implies that the market for trucking capacity is likely to remain tight into the end of the year. If the economy grows at about a 5-6% rate this year, and at a 3% rate next year, there is likely to still be support for rate growth in 2022, resulting in an environment more similar to 2011-2012, where rates were supported for two years past the peak in spot rates.
This commentary originally appeared in the May 2021 issue of Heavy Duty Trucking magazine.
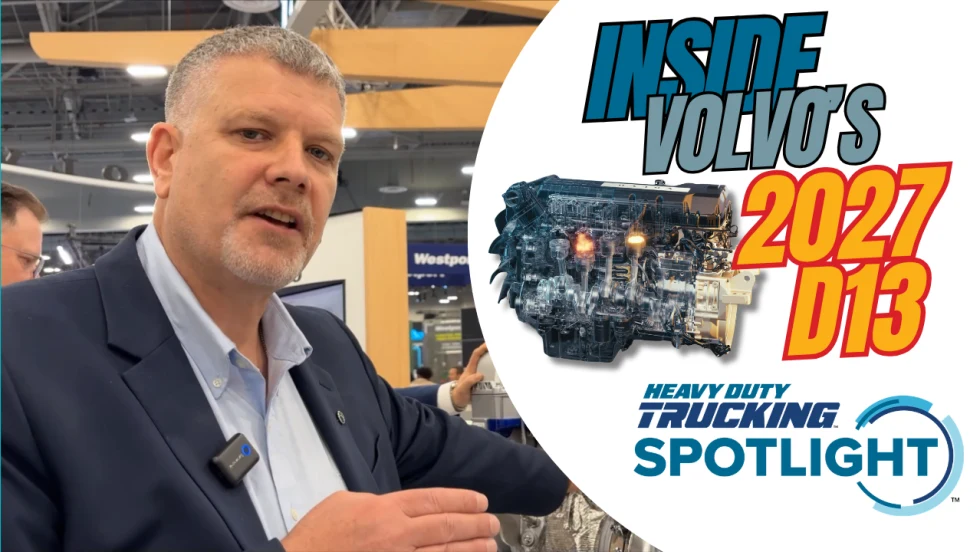
Volvo’s updated D13 promises lower emissions without sacrificing performance or fuel economy. Take a closer look at what changed inside the engine in this HDT Spotlight video.
Read More →
The Michelin X Multi Energy D2 is a regional haul drive tire engineered to help fleets improve fuel efficiency, durability and traction in demanding stop-and-go operations.
Read More →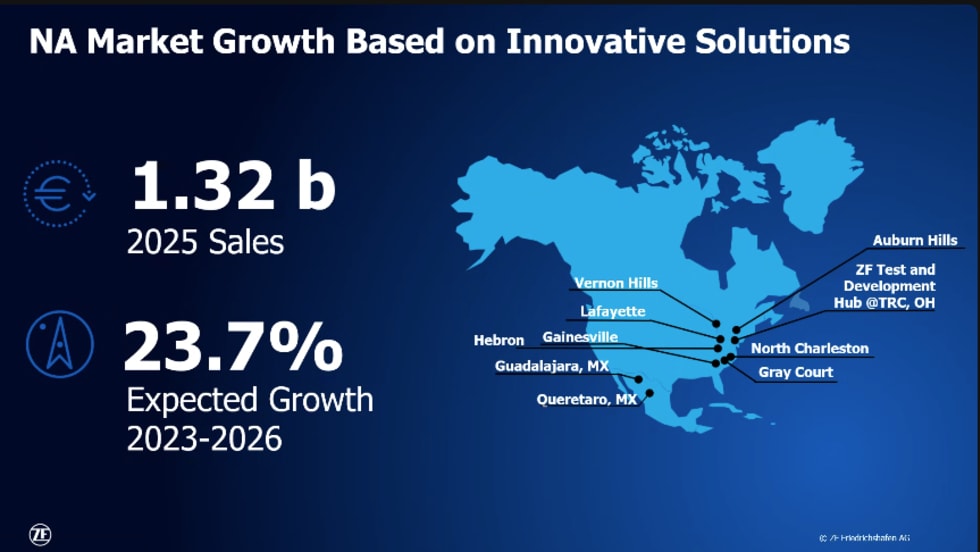
ZF is expanding its North American commercial-vehicle presence with new transmission applications, electrification, trailer technology and autonomous-driving systems.
Read More →
Could Tesla’s camera-only autonomous driving technology work on an 80,000-pound Semi? In this commentary, HDT's Deborah Lockridge takes a look at Tesla, Cybercab, and how autonomous trucks see the road.
Read More →
Kodiak AI says its driverless long-haul safety case is 93% complete and it remains on track to begin commercial operations by year-end 2026.
Read More →
The U.S. Department of Transportation issued a new automated-vehicle strategy that outlines plans for driverless-truck regulations, cross-state freight corridors, and federal safety standards.
Read More →
The Port Authority of New York and New Jersey announced millions in incentives for zero-emission drayage trucks, yard tractors, and new charging hubs near the port.
Read More →
A SPAC deal could provide PlusAI with up to $300 million as it works toward a 2027 commercial launch of factory-built autonomous trucks.
Read More →
The National Highway Traffic Safety Administration says it lacks authority to regulate medium- and heavy-duty truck engines separately from complete vehicles, but the existing standards have not yet been eliminated.
Read More →
Detroit isn’t starting from scratch to meet EPA 2027 diesel emissions standards. Its Gen 6 DD13 and DD15 engines keep much of today’s platform while updating the fuel and aftertreatment systems.
Read More →