Economic Watch: Employment, Manufacturing Disappoint; Construction Skyrockets
Despite a booming construction sector, the latest reports on jobs and manufacturing have some concerned that the U.S. economy is losing some of its steam.

Despite a booming construction sector, the latest reports on jobs and manufacturing have some concerned that the U.S. economy is losing some of its steam.
Employers added just 142,000 non-farm jobs in the country during September, according to Labor Department figures released Friday, far short of what many analysts were expecting. The nation’s unemployment rate was unchanged from August at 5.1%.
The number of jobs added during August was also revised downward sharply, from an originally reported 173,000 down to 136,000. Combined with July’s downward revision, employment gains for the two months combined were 59,000 less than previously reported.
So far in 2015, job growth has averaged 198,000 per month, compared with an average monthly gain of 260,000 in 2014.
In for-hire trucking there were 4,000 job losses for September, while the wider transportation and warehousing sector added 3,500.
The number of total September job additions is also far below an estimated 200,000 jobs additions for the month released earlier in the week by payroll processor ADP.
Manufacturing Looking Relatively Dismal
A separate report from the U.S. Commerce Department released Friday showed significant declines in factory activity during August.
New orders for manufactured goods fell 1.7% following two straight monthly increases. This includes a 2.3% drop in new orders for long-lasting durable goods following a 1.9% increase in July. Shipments of durable goods fell 0.2% following two straight monthly gains. Both orders and shipments were revised down from an earlier report. A drop in the transportation category led each.
Declines were also seen in orders and shipments of nondurable goods during August.
This followed a report the day before from the nation’s purchasing managers showing manufacturing growth in September slowed to its lowest level since May 2013 amidst broad-based declines.
The Institute for Supply Management’s index of factory activity fell from 51.1% in August to 50.2% in September. It still remains above the level of 50%, indicating expansion in the sector, albeit a slower expansion.
Its measure of new orders fell to the lowest level since November 2012, as only seven of the 18 manufacturing industries reported overall growth in September.
But Look at Construction
These reports are in sharp contrast to one from Thursday showing total U.S. construction spending during August hit its highest level since May 2008, marking the ninth consecutive monthly gain.
Gains were reported in private residential building, the best pace since January 2008, along with those in public construction, and in non residential building, which hit its highest level since November 2008.
Making sense of the numbers
So what does all of this say about the economy and the big question of how the Federal Reserve will react as it considers a hike in interest rates for the first time in years? As usual, it depends on who you ask.
“Most of the labor market indicators would imply a weakening in labor market conditions," said Paul Ferley, assistant chief economist at RBC Economics. "However, the current unemployment rate of 5.1% is within the range of 4.9%-5.2%, which Fed officials regard as representing full employment. Thus, some moderation in measures such as the monthly increase in payrolls may reflect the U.S. economy coming up against capacity limits.”
He said indications of slowing employment growth would provide a reason for the Fed to stay on the sidelines. However, to the extent that this reflects labor markets moving toward full capacity, the argument to raise interest rates becomes stronger. Upcoming comments by Fed officials will be monitored closely to gauge how these job numbers are being viewed.
In contrast, Lindsey Piegza, chief economist at Stifel Fixed Income, contends that the jobs report was downright disappointing no matter how you slice it.
“Headline weakness coupled with nonexistent wage growth, and a further decline in the participation rate, suggests the U.S. labor market is undergoing a significant slowdown in the second half of the year,” she said. “Furthermore, keep in mind, weakness in the labor market generally translates into weakness in headline economic activity as well.”
She notes the economy was growing at 2.2% in the first half of the year, a significant slowdown in growth that would translate into an annual growth rate below 2%. That's below the average activity level since the end of the Great Recession, and further below the Fed’s internal expectations for 2015 growth.
“From the Fed's perspective, I imagine they are thinking one word. 'Phew! Thank goodness we bypassed [a rate increase in] September,'” Piegza said. “With two consecutive months of significant headline weakness, in our opinion, October is very much off the table, as is a rate increase by the end of the year.”
There are also conflicting views on the manufacturing reports.
“The disappointing performance came on the heels of a firm GDP print for the second quarter of 2015 and is in sharp contrast to the recent decade-high recorded by the non-manufacturing index,” said Laura Cooper, economist at RBC Economics. “This divergence highlights the underlying dynamics of U.S. activity, with ongoing strength in the domestic side of the economy expected to offset external malaise to keep the economy on track to sustain an above-potential pace for the remainder of 2015.”
Not so, Piegza argued, noting amid deterioration in global demand, manufacturing activity has continued to slip, falling to breakeven, the lowest reading in more than two years.
“Barely in positive territory, U.S. manufacturing is on the brink of contraction, flirting with falling below [a reading of] 50 for the first time since November 2012,” she said. “After all, the widespread weakness in the underlying components, including new orders and orders backlog, suggests further weakness is coming down the pipeline for the fourth quarter.”
While the wave of economic reports next week will ease, other readings on how the economy and business will soon be out as the third quarter corporate earnings season kicks off in a few days.
More Fleet Management
Kodiak Lines Up Fleets for Driverless Trucking
An agreement for 75 trucks, a new Texas freight lane, and progress on safety validation move Kodiak closer to its planned driverless highway launch.
Read More →
ITS Logistics Settles Religious Harassment Case
The Nevada-based logistics firm agreed to pay more than $396,000 to settle a religious harassment charge involving an employee's Jewish identity.
Read More →
Your Trucks Are Busy. That Doesn’t Mean They’re Winning.
High utilization doesn’t always mean strong margins. Looking beyond the current load can help fleets make better dispatch decisions and get more value from each truck’s time.
Read More →
Why This Trucking Recovery Is Different
Freight demand remains sluggish, but rising costs and tougher enforcement have taken enough capacity out of the market to change the outlook for motor carriers.
Read More →
Platform Science Adds Dispatch and Safety Tools
Four additions to PS Fleet help fleets monitor loads, manage driver coaching, share truck locations and adjust video system settings.
Read More →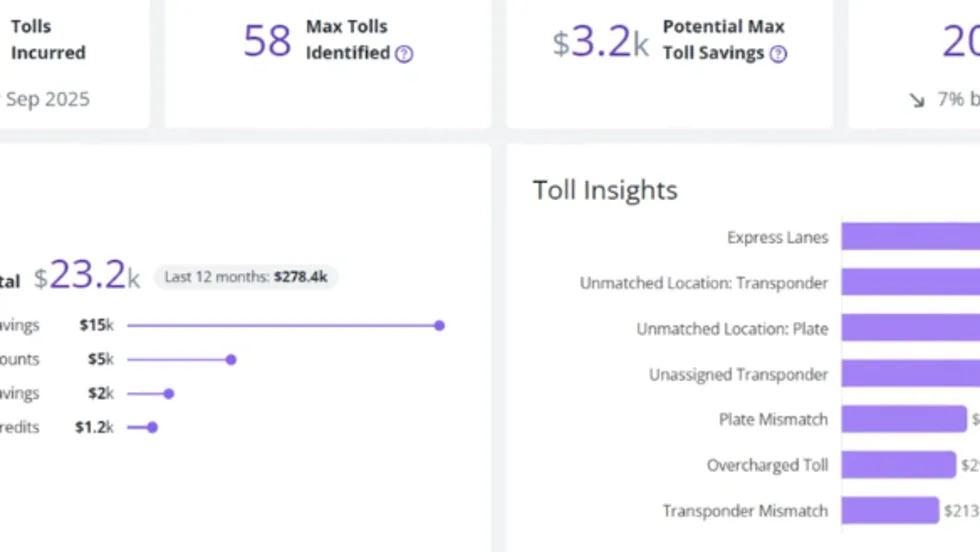
PrePass Intelligence Mines Fleet Bypass, Toll and Safety Data
PrePass Intelligence helps fleets measure bypass savings, flag potential toll overcharges, and spot suspicious transactions by combining data from separate systems.
Read More →
Motive Adds AI Agents for Fleet Operations
New tools automate follow-up on fleet data, from maintenance work orders to driver alerts, with two-way voice conversations planned for later this year.
Read More →
Can You Beat Our Trucking Trivia Challenge?
Test your truck knowledge with 19 trivia questions from Heavy Duty Trucking Exchange. Can you keep up with the fleet pros?
Read More →
BeyondTrucks Adds Rules Checks to Dispatch
New Compatibility Engine checks driver qualifications, equipment requirements and fleet policies before loads are dispatched.
Read More →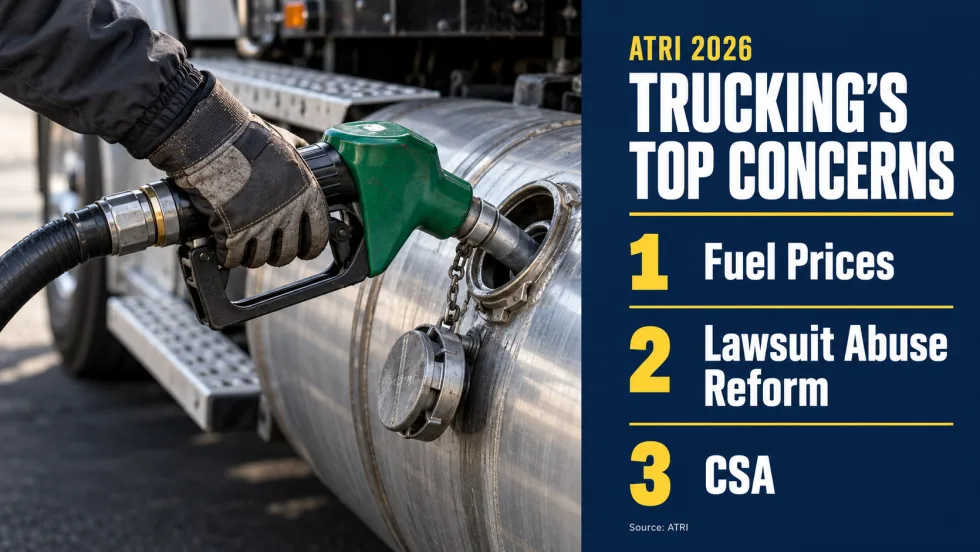
Diesel Prices Hijack Trucking’s Worry List
ATRI’s annual survey finds cautious optimism about freight, but diesel costs, litigation, and insurance continue to squeeze fleets. Drivers have different priorities on several issues.
Read More →