
Related: Carrier Earnings Worse than the Economy Might Indicate [Commentary]
Where are we headed in 2020? [Commentary]
For the third time this year, the economy seems to be doing better than trucking markets.
January 3, 2020
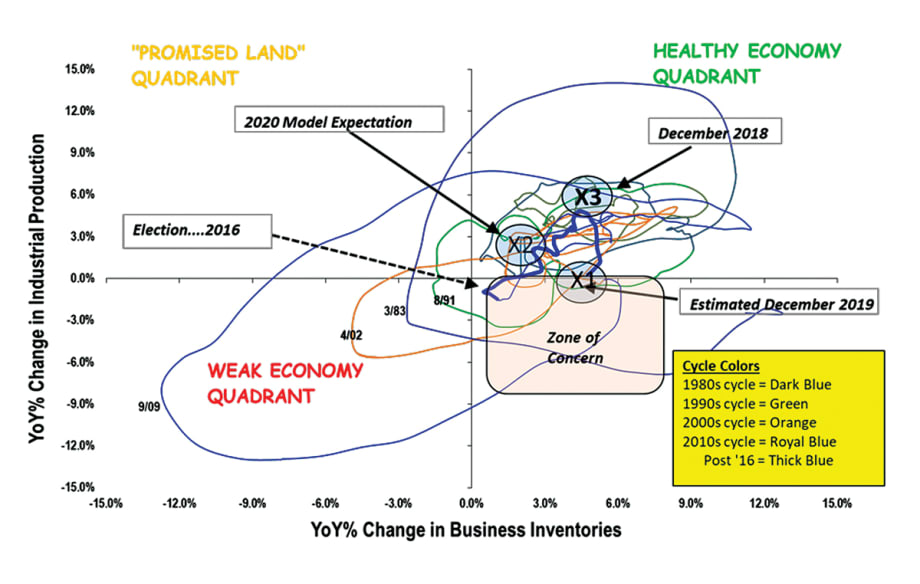
A number of factors could change the direction of our chart in 2020, including trade policy, interest rates, inventory levels, and truck industry regulations.
Source: Tahoe Ventures, LLC Estimates, Federal Reserve, Department of Census
3 min to read
For the third time this year, the economy seems to be doing better than trucking markets. Let’s dig into third-quarter earnings reports from publicly traded fleets for more.
Over the past few months, I have written about declining trends in several areas, including fleet profitability, aggregate industrial production as measured by the data released by the government, and railroad car data, which continues to reflect a negative 5-6% growth rate. What does that mean for 2020? To help answer that, I’m bringing back the Business Cycle (“spaghetti”) chart last seen as we looked ahead to 2019.
In the graphic below, which measured growth rates of industrial production (north/south) and business inventories (east/west), we are currently following along the same track that became the recession of 2001. However, we have to look at where we were, where we are going, and what other activities could impact that direction. What this chart measures is not only direction, but also economic velocity. Generally, north and east is good (positive and accelerating momentum), and south and west is bad (slowing production or inventory liquidation).
We began 2019 at the point marked X3, with about 4-5% industrial production growth, about 6% truck tonnage growth, and about 4-5% inventory growth. Following the thick blue line, you can see that over the course of 2019, we moved almost directly south, only making a turn to the left in the final quarter of the year (point X1). We are now staring at negative industrial production growth rates of 1-2%, and inventories still growing at a 4.5% rate. This is simply not sustainable. Based on past trends, we will continue to see sluggish truck tonnage and industrial production levels until the inventory growth rate is at least in line with overall GDP growth (1.7%-1.9%). This should take at least six months, possibly nine to 12, implying that tonnage/mileage for fleets will likely remain negative until at least mid-year 2020. This puts the market expectations of 1.5%-2% truck freight growth rates in 2020 at risk (point X2).
Now step back and let’s consider some regulatory and geopolitical factors that could change the direction of our chart in 2020: trade policy, interest rates, inventory levels, and truck industry regulations.
Media reports at press time indicated we could be not only on the verge of a Phase One trade deal with China, but we also should get some increased visibility on Brexit and the U.S.-Mexico-Canada Trade Agreement. The passage of, or even increased visibility of, these items could result in businesses deciding they can hold less inventory, and get us to a more balanced inventory/industrial production growth rate quicker. Similarly, many economists believe that there are signs of economic stability in the global economy, and given the strength of the U.S. consumer, the Federal Reserve could move to a more stable position on interest rates, holding at current levels.
The combination of these events should help bring down business inventories at a faster level, but we don’t see inventories getting to proper levels to support freight growth rates in excess of economic growth rates until at least late summer or into fall.
Finally, new regulation may help reduce driver capacity and raise freight rates, including increased use of hair testing, the new federal Drug & Alcohol Clearinghouse, and full implementation of the electronic logging device mandate that went into effect last month. Carrier bankruptcies such as Celadon’s recent closure may further reduce fleet capacity, and more carrier failures are likely, given rising insurance and still-weak spot rates.
While these factors could lead to a stronger rate structure in the industry and improved profits later in 2020, the story for the near term in 2019 and early 2020 will remain, “too many trucks for too little freight.” The result will be declining pricing and increased pressure on carrier profits.
Subscribe to Our Newsletter
More Fleet Management
Kodiak Lines Up Fleets for Driverless Trucking
An agreement for 75 trucks, a new Texas freight lane, and progress on safety validation move Kodiak closer to its planned driverless highway launch.
Read More →
ITS Logistics Settles Religious Harassment Case
The Nevada-based logistics firm agreed to pay more than $396,000 to settle a religious harassment charge involving an employee's Jewish identity.
Read More →
Your Trucks Are Busy. That Doesn’t Mean They’re Winning.
High utilization doesn’t always mean strong margins. Looking beyond the current load can help fleets make better dispatch decisions and get more value from each truck’s time.
Read More →
Why This Trucking Recovery Is Different
Freight demand remains sluggish, but rising costs and tougher enforcement have taken enough capacity out of the market to change the outlook for motor carriers.
Read More →
Platform Science Adds Dispatch and Safety Tools
Four additions to PS Fleet help fleets monitor loads, manage driver coaching, share truck locations and adjust video system settings.
Read More →
PrePass Intelligence Mines Fleet Bypass, Toll and Safety Data
PrePass Intelligence helps fleets measure bypass savings, flag potential toll overcharges, and spot suspicious transactions by combining data from separate systems.
Read More →
Motive Adds AI Agents for Fleet Operations
New tools automate follow-up on fleet data, from maintenance work orders to driver alerts, with two-way voice conversations planned for later this year.
Read More →
Can You Beat Our Trucking Trivia Challenge?
Test your truck knowledge with 19 trivia questions from Heavy Duty Trucking Exchange. Can you keep up with the fleet pros?
Read More →
BeyondTrucks Adds Rules Checks to Dispatch
New Compatibility Engine checks driver qualifications, equipment requirements and fleet policies before loads are dispatched.
Read More →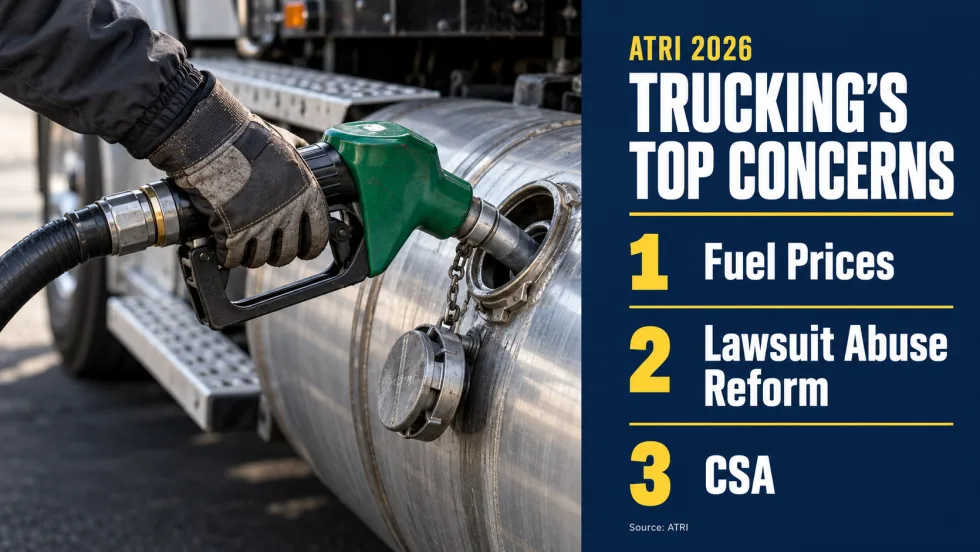
Diesel Prices Hijack Trucking’s Worry List
ATRI’s annual survey finds cautious optimism about freight, but diesel costs, litigation, and insurance continue to squeeze fleets. Drivers have different priorities on several issues.
Read More →