Economic Watch: GDP Growth Improves, Still Weak; Consumers Happy
Despite the nation’s gross domestic product in the first quarter of the year moving higher than first thought, growth remains at its lowest level since the first quarter of 2015, according to a Commerce Department report released Friday. Yet a separate survey shows this has yet to damper consumers’ feelings.

Despite the nation’s gross domestic product in the first quarter of the year moving higher than first thought growth, remains at its lowest level since the first quarter of 2015, according to a Commerce Department report released Friday. Yet a separate survey shows this has yet to damper consumers’ feelings
This broadest measure of the nation’s economic performance, expanded at an 0.8% annual rate in the first three months of the year, less than a consensus estimate by Wall Street analysts, but better than the 0.5% GDP estimate of a month ago.
This latest performance compares to a fourth quarter 2015 pace of 1.4% and a 2015 high of 3.9% in the second quarter.
The Wall Street Journal reported the reason for the latest uptick is that corporate after-tax profits rebounded, while there was “a larger gain for residential investment and smaller drags on overall growth from private inventories and foreign trade.”
Despite the increase in profits they are down 3.6% from a year earlier, which is being attributed to a pull-back in business investment. This also follows a report from the day before showing business investment did not improve in April.
Even with the upward revision, growth in the first quarter remains disappointingly below the economy’s long-run potential or average rate, according to Paul Ferley, Assistant Chief Economist, RBC Economics.
“The quarter did indicate some areas of impressive strength with residential investment growth of 17.2%, which represented an upward revision from the previously-estimated 14.9%. Consumer spending continued to rise, albeit at a relatively modest, and unrevised, pace of 1.9%. The decline in exports was lessened to 2% from a 2.6% previous decline,” he said. “Imports are now estimated to have declined 0.2% as compared to the previously-estimated 0.2% increase.”
Ferley said the build in inventories still slowed in the first quarter though not to the same extent as previously estimated, with the subtraction from overall GDP growth being lessened. The inventory component has now subtracted from growth for three consecutive quarters. A main source of weakness was business investment dropping 6.2%, which represented a slight downward revision from the previously estimated 5.8% drop.
“Some initial data for the second quarter, such as the strong April retail sales report, provide optimism that the slowing trend is not continuing into the current quarter,” he said. “Optimism about a strengthening in consumer spending was additionally provided in today’s report with the first quarter savings rate being revised up sharply to 5.7% from the previously estimated 5.2%. Our forecast projects an annualized second quarter GDP increase of 2.9%.”
However, Stifel Fixed Income Chief Economist Lindsey Piegza warned the minimal increase in the GDP does little to reinforce optimism of better times ahead.
“Keep in mind, even at 0.8% in the first quarter, coupled with an expected rise of near 2% growth in second quarter, the average pace of expansion across the first six months of the year falls well short of the moderate 2% trend established since the end of the Great Recession,” she said. “In other words, at 0.5% or 0.8%, the premise remains the same: weak growth, a fragile consumer and negative business investment January to March.”
She believes with this latest report “hawks” at the U.S. Federal Reserve, already shrugging off the weakness at the start of the year, will no doubt highlight any additional upward revision as support to their view of fundamental strength in the U.S. economy and further evidence an interest rate hike less than four weeks from now is appropriate.
“Remember, the Fed is not looking for strong or robust or solid, just less weakness coupled with a potential side of ‘moderate’ conditions to come over the near to medium term,” Piegza said. “At this point, more important than splitting hairs over weak or a slightly less weak first quarter GDP report, the upcoming April consumption and May employment reports ahead of the June Federal Open Market Committee meeting will offer clear telltale signs of whether or not the weakness January to March was temporary or if earlier weakness will persist, carrying over in the second-quarter and beyond.”
Consumers Sentiment Best In Nearly A Year
Meantime, a separate report, also released Friday, shows consumers remain upbeat, but a little less so than compared to a preliminary survey earlier in the month, but much better than April, according to the final May results of the University of Michigan Survey of Consumers.
Its Index of Consumer Sentiment posted gains of 6.4% from April and 4.4% from a year earlier, its biggest monthly increase since 2013 and its highest level since last June.
Also survey measures of consumer feelings about current economic conditions increased 3% month-over-month and 9% from May 2015, while a gauge of consumer expectations jumped 9.4% this month from April, but posted a much smaller gain of 0.8% from the same time last year.
“Despite the meager GDP growth as well as a higher inflation rate, consumers became more optimistic about their financial prospects and anticipated a somewhat lower inflation rate in the years ahead,” said Surveys of Consumers Chief Economist Richard Curtin. “Positive views toward vehicle and home sales also posted gains in May largely due to low interest rates.”
He said the biggest uncertainty consumers see on the horizon is not whether the Fed will hike interest rates in the next few months, but rather the outlook for future government economic policies under a new president.
“This has increased their emphasis on maintaining precautionary savings, although the savings rate is not expected to increase much beyond its current level,” Curtin said. “Although small stock gains are anticipated, household wealth is more likely to benefit from rising home prices, with gains now more frequent than in a decade.”
Overall, he said the number indicate that inflation-adjusted consumer expenditures can be expected to rise by 2.5% in 2016 and 2.7% in 2017.
More Fleet Management
Your Trucks Are Busy. That Doesn’t Mean They’re Winning.
High utilization doesn’t always mean strong margins. Looking beyond the current load can help fleets make better dispatch decisions and get more value from each truck’s time.
Read More →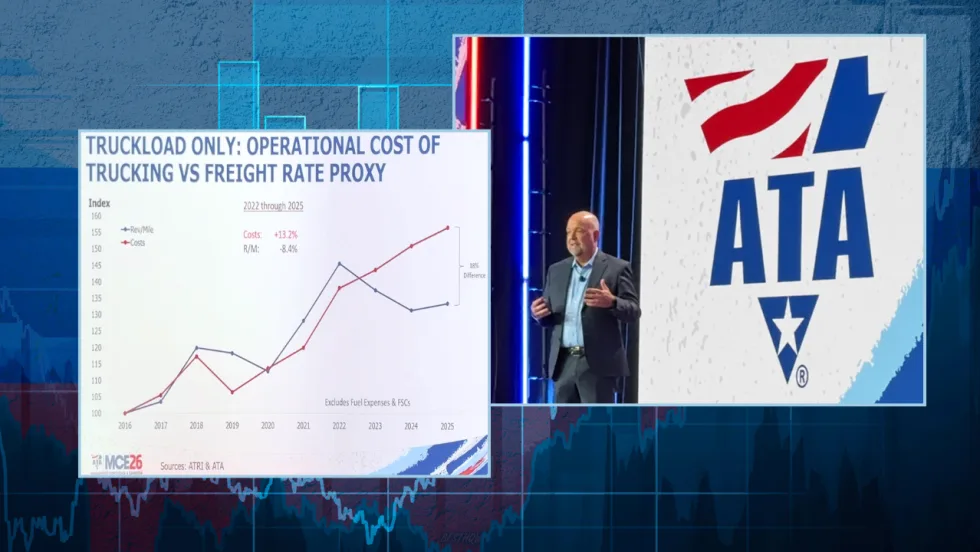
Why This Trucking Recovery Is Different
Freight demand remains sluggish, but rising costs and tougher enforcement have taken enough capacity out of the market to change the outlook for motor carriers.
Read More →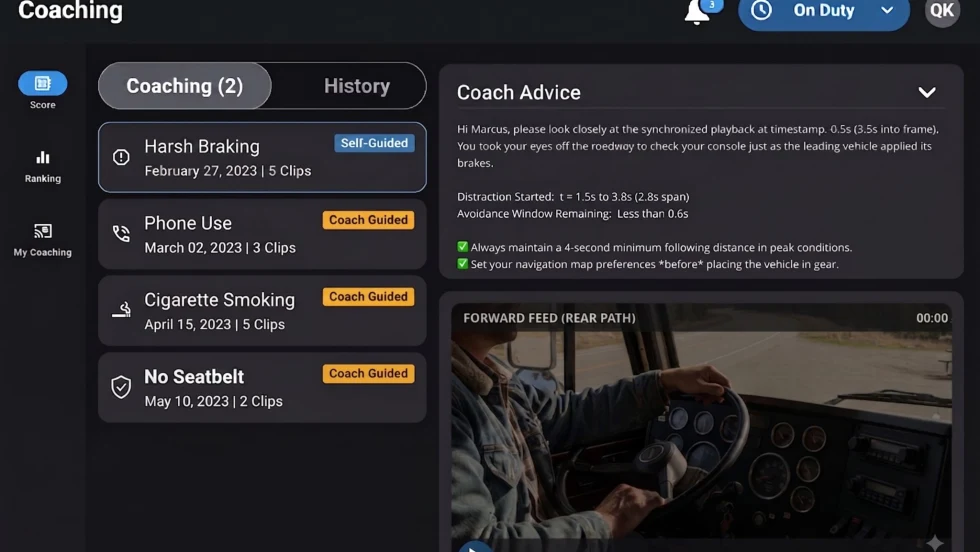
Platform Science Adds Dispatch and Safety Tools
Four additions to PS Fleet help fleets monitor loads, manage driver coaching, share truck locations and adjust video system settings.
Read More →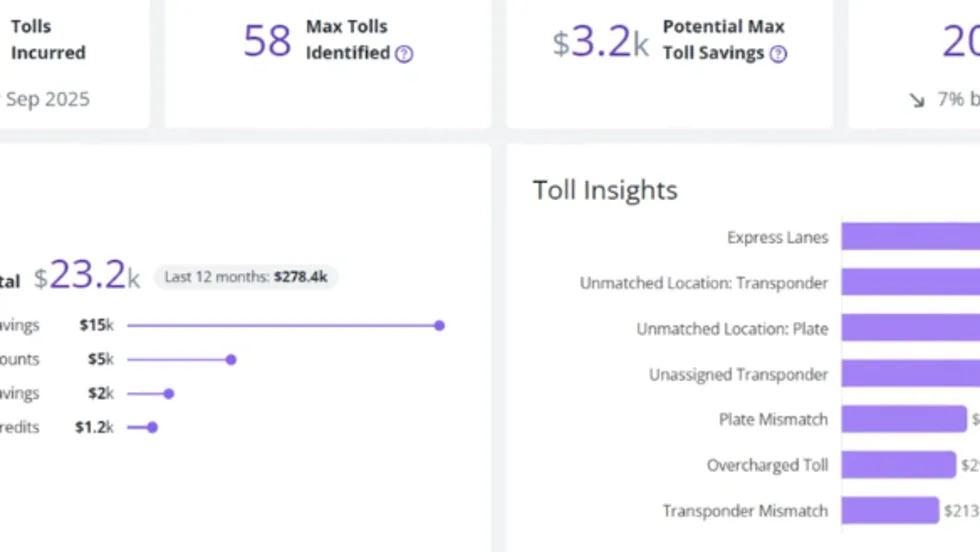
PrePass Intelligence Mines Fleet Bypass, Toll and Safety Data
PrePass Intelligence helps fleets measure bypass savings, flag potential toll overcharges, and spot suspicious transactions by combining data from separate systems.
Read More →
Motive Adds AI Agents for Fleet Operations
New tools automate follow-up on fleet data, from maintenance work orders to driver alerts, with two-way voice conversations planned for later this year.
Read More →
Can You Beat Our Trucking Trivia Challenge?
Test your truck knowledge with 19 trivia questions from Heavy Duty Trucking Exchange. Can you keep up with the fleet pros?
Read More →
BeyondTrucks Adds Rules Checks to Dispatch
New Compatibility Engine checks driver qualifications, equipment requirements and fleet policies before loads are dispatched.
Read More →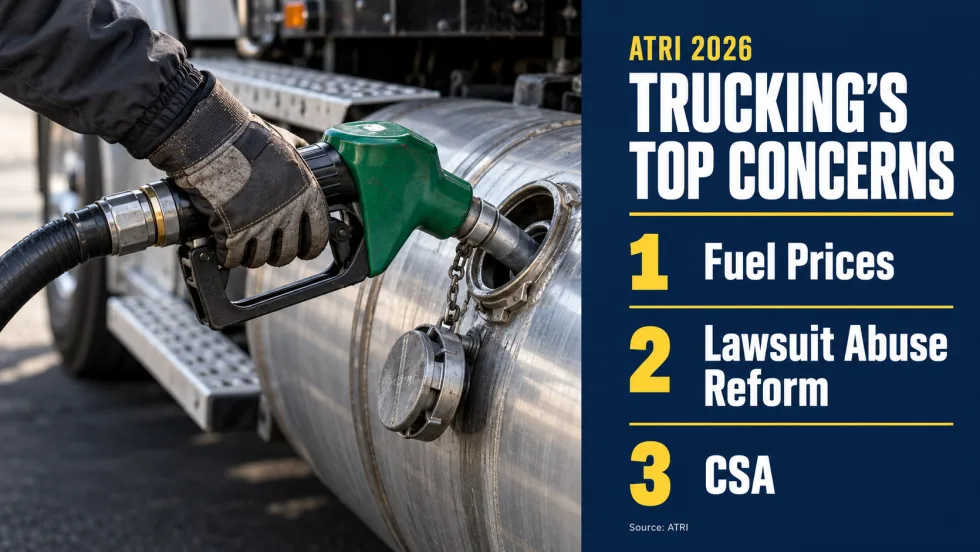
Diesel Prices Hijack Trucking’s Worry List
ATRI’s annual survey finds cautious optimism about freight, but diesel costs, litigation, and insurance continue to squeeze fleets. Drivers have different priorities on several issues.
Read More →
Nomination Deadline Extended for HDT Emerging Leaders
Just a few more days to nominate accomplished trucking fleet professionals under 40 who are making an impact and helping lead the industry forward for the HDT Emerging Leaders award. Deadline extended to October 20!
Read More →
What Will ATA’s New Leader Bring to Trucking's Table?
Incoming President and CEO Mark Colson’s record in Alabama offers clues about his priorities and approach following Chris Spear’s abrupt departure as the head of the American Trucking Associations.
Read More →