

Wabash Profit Increases, Meritor up on Adjusted Basis
Wabash's second quarter earnings showed a big leap in profitability from a year ago. Meritor results were hampered by a strong dollar and weak overseas markets but were up on an adjusted basis.

UPDATED – Trailer Maker Wabash National Corp. (WNC) second quarter earnings showed a big leap in profitability from a year ago, including some record numbers. Meritor saw its results hampered by a strong dollar and weak overseas markets but reported income gains on an adjusted basis.
Wabash National
Wabash net income totaled $28.6 million, or 41 cents per diluted share, compared to net income of $16.2 million, or 23 cents per diluted share a year earlier.
For the second quarter of 2015, net sales increased 6% to $515 million from $486 million in the prior year quarter. Operating income rose 24% to a record quarter of $42.1 million, compared to $33.9 million during the same time in 2014.
Commercial trailer products led the way, said President and CEO Dick Giromini. “New trailer shipments for the second quarter were approximately 16,900, coming in at the top-end of our previous guidance of 16,000 to 17,000 trailers. The year-over-year increase in total trailer demand, as evidenced by our strong backlog of $1.1 billion, along with ongoing demand strength being projected by both ACT Research and FTR, provides us even greater confidence that 2015 will prove to be our fourth consecutive year of record performance.”
The company raised its full-year shipment and adjusted earnings guidance to between 63,000 to 66,000 trailers and between $1.25 to $1.35 per diluted share.
Wabash’s commercial trailer products division achieved new quarterly records for net sales, gross margin and operating income. Net sales were $395 million, an increase of 17.4%, on shipments of 16,150 trailers, or 2,250 more trailers than the prior year period. Gross profit margin increased $18.2 million, while operating income increased by $17 million to $39 million from the second quarter last year.
The company’s diversified products operation, which includes composite materials operations and liquid tank systems, saw net sales fall $21 million, or 17.9%, compared to the previous year period. This was primarily due to reduced demand for composite product offerings and non-trailer related equipment, as well as fewer tank trailer shipments due to delays in customer pick-ups, according to Wabash.
The retail division net sales, which includes the company’s network of new and used trailer sales, parts and service locations, was $45 million, a decrease of 11.9% compared with the prior year. Wasbash said this was primarily due to fewer retail locations resulting from the transition of three West Coast locations to independent dealers in May 2014, as demand for trailers and parts and service remained healthy throughout the quarter. On a same store basis, net sales increased 5% compared with the prior year period.
Further details are on the Wabash National website.
Meritor
Truck component manufacturer Meritor (MTOR) saw far lower net profit than the same quarter a year ago, but that was because last year's numbers included $209 million from the antitrust settlement with Eaton Corp. Earnings were up on an adjusted basis.
For its third fiscal quarter ending June 30, Meritor's net income from continuing operations was $15 million, or 15 cents per diluted share, compared with $237 million, or $2.34 per diluted share a year earlier.
However, adjusted net income from continuing operations was $41 million, or adjusted diluted earnings per share of $0.41, up from $29 million, or $0.29, in the prior year.
Sales totaled $909 million, down 7%, during the same time frame. This decrease was due to currency exchange rate declines in Europe and Brazil against the U.S. dollar. When adjusted for the impact of foreign currency, sales for the period increased 1% from a year ago, according to the company.
Commercial Truck & Industrial segment sales were $705 million, down 7%, compared with the same period last year.
“Revenue was unfavorably impacted by the strengthening U.S. dollar against most currencies – especially the euro and the Brazilian real. Higher truck production in North America, driven by a strong Class 8 market, offset lower production in South America and China,” the company said in a statement.
The segment’s earnings before interest, taxes, depreciation and amortization (EBITDA) was $58 million for the quarter, up $3 million from the third quarter of fiscal year 2014.
Meritor’s Aftermarket & Trailer segment posted sales of $233 million, down 8% from the same period last year.
The unfavorable impact of the strengthening U.S. dollar against the euro drove lower revenue in the company's aftermarket business in Europe, according to the company.
Segment EBITDA was $31 million, compared with $28 million in the third quarter of fiscal year 2014.
While Meritor made no change to expectations for revenue for this year, in the range of $3.5 billion to $3.55 billion, it revised adjusted EBITDA margin to approximately 9.3%, compared with prior guidance of 9% to 9.2%. It expects adjusted diluted earnings per share from continuing operations will range from $1.40 to $1.50, as compared with prior guidance of $1.30 to $1.40.
It also noted that it has secured standard product positioning with Paccar for front axles in North America. This follows an agreement with Paccar early this year for preferred positioning on rear axles in North America and Australia.
There is more information on the Meritor website.
Updated 2 p.m. EDT August 4, 2015, to include Meritor adjusted net income accounting for previous year's Eaton antitrust settlement.
More Equipment
How Volvo Updated Its D13 for EPA 2027 [Watch]
Volvo’s updated D13 promises lower emissions without sacrificing performance or fuel economy. Take a closer look at what changed inside the engine in this HDT Spotlight video.
Read More →
Michelin Tire Improves Efficiency and Durability for Regional Fleets
The Michelin X Multi Energy D2 is a regional haul drive tire engineered to help fleets improve fuel efficiency, durability and traction in demanding stop-and-go operations.
Read More →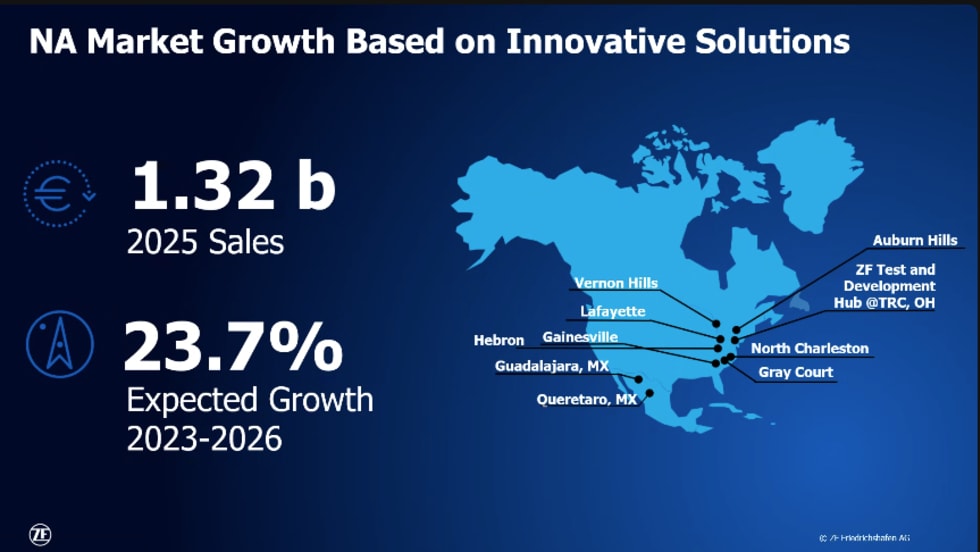
ZF Expands Commercial Vehicle Push in North America
ZF is expanding its North American commercial-vehicle presence with new transmission applications, electrification, trailer technology and autonomous-driving systems.
Read More →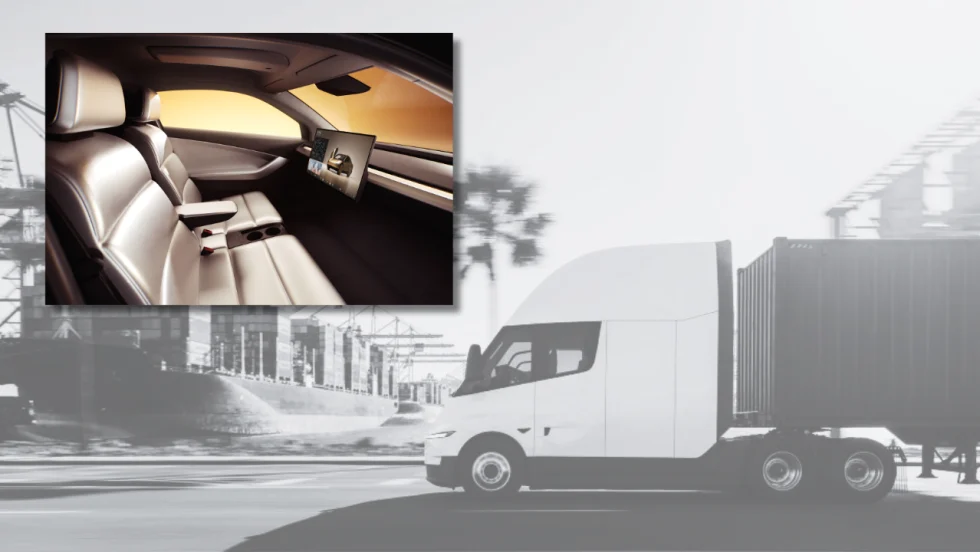
Tesla Wants a Self-Driving Semi. Are Cameras Enough?
Could Tesla’s camera-only autonomous driving technology work on an 80,000-pound Semi? In this commentary, HDT's Deborah Lockridge takes a look at Tesla, Cybercab, and how autonomous trucks see the road.
Read More →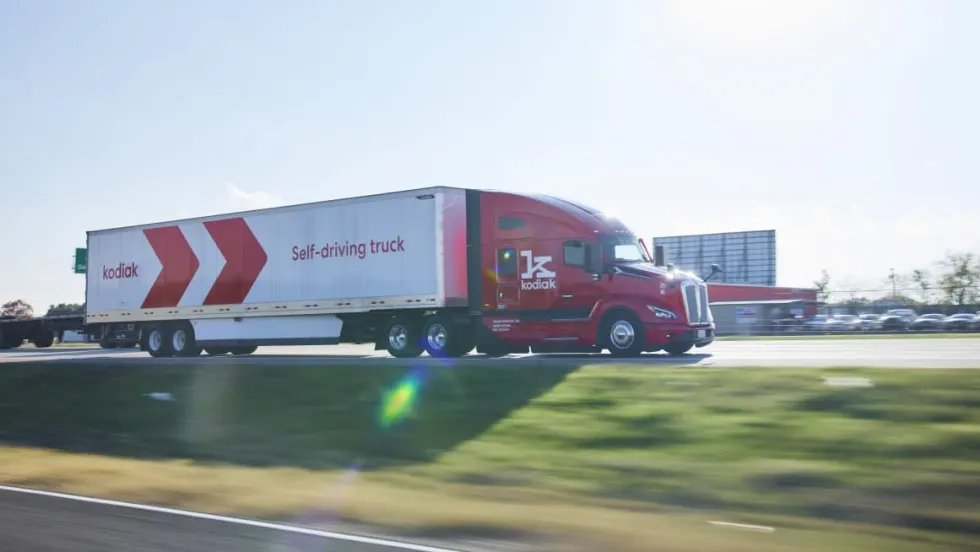
Kodiak: Driverless Long-Haul Truck Launch on Track for 2026
Kodiak AI says its driverless long-haul safety case is 93% complete and it remains on track to begin commercial operations by year-end 2026.
Read More →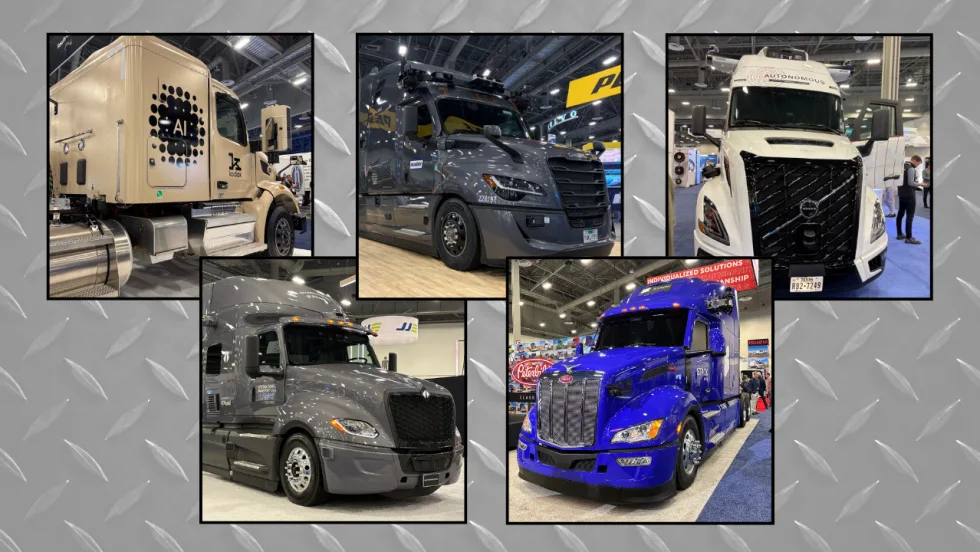
What DOT’s Automated Vehicle Strategy Means for Trucking
The U.S. Department of Transportation issued a new automated-vehicle strategy that outlines plans for driverless-truck regulations, cross-state freight corridors, and federal safety standards.
Read More →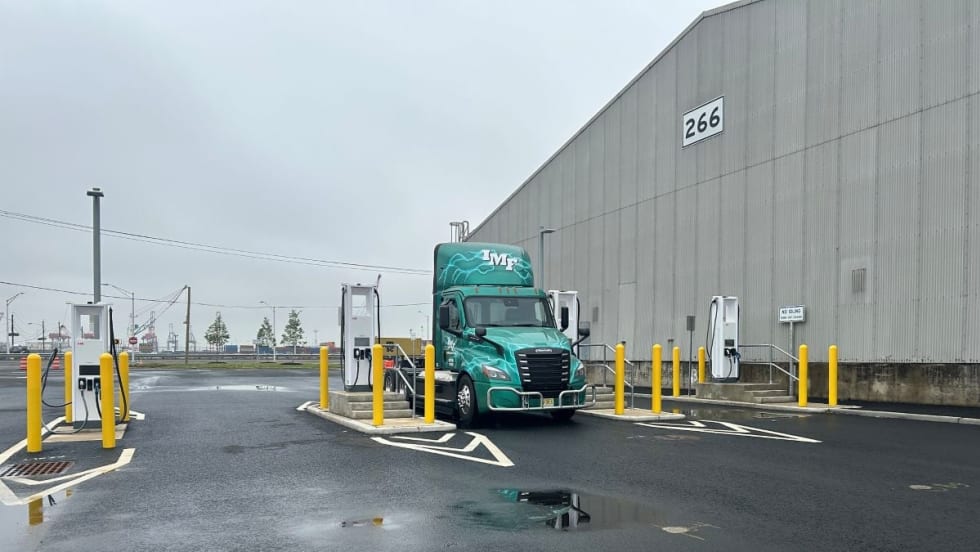
East Coast Port Launches $45M Electric Truck Push
The Port Authority of New York and New Jersey announced millions in incentives for zero-emission drayage trucks, yard tractors, and new charging hubs near the port.
Read More →
PlusAI Going Public to Fund Autonomous Truck Launch
A SPAC deal could provide PlusAI with up to $300 million as it works toward a 2027 commercial launch of factory-built autonomous trucks.
Read More →
NHTSA Moves to Rewrite Truck Fuel-Economy Rules
The National Highway Traffic Safety Administration says it lacks authority to regulate medium- and heavy-duty truck engines separately from complete vehicles, but the existing standards have not yet been eliminated.
Read More →
Detroit Opens Orders for EPA 2027 Engines
Detroit isn’t starting from scratch to meet EPA 2027 diesel emissions standards. Its Gen 6 DD13 and DD15 engines keep much of today’s platform while updating the fuel and aftertreatment systems.
Read More →