Economic Watch: Manufacturing, Construction Remain on Firm Ground
Economic activity in the nation’s manufacturing sector remained solid during March, while construction spending was nearly unchanged in February. The latest reports show the nation’s overall economic health was stronger in the final quarter of last year than earlier indications.

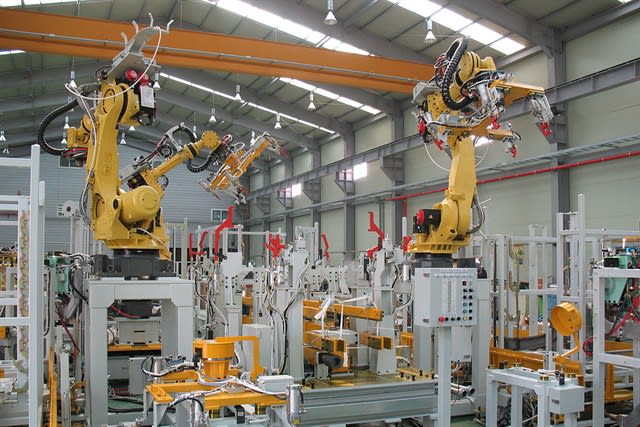
Two indices show manufacturing continues to expand, but analysts raised concerns about new Trump administration tariffs.Photo by Mixabest via Wikimedia Commons
Economic activity in the nation’s manufacturing sector remained solid during March, while construction spending was nearly unchanged in February. The latest reports show the nation’s overall economic health was stronger in the final quarter of last year than earlier indications.
Manufacturing Activity Still Expanding
Manufacturing activity continued expanding in March, but at a slower rate than the month before, according to latest figures from the Institute for Supply Management (ISM). Its Purchasing Managers’ Index registered 59.3%, a decrease of 1.5 percentage points from the February reading of 60.8%.
A reading above 50% indicates manufacturing is expanding, while below 50% signals contraction.
The New Orders Index registered 61.9%, a drop of 2.3 percentage points from the February reading. The Production Index registered 61%, a 1 percentage point decrease compared to the month before.
Despite the overall downturn, comments from the panel of purchasing executives reflected continued expanding business strength, with 17 of the 18 manufacturing industries surveyed reporting growth in March.
“This indicates strong growth in manufacturing for the 19th consecutive month, led by continued expansion in new orders, production activity, employment and inventories, with suppliers continuing to struggle delivering to demand,” said Timothy R. Fiore, chair of the ISM Manufacturing Business Survey Committee.
A separate but similar survey from IHS Markit indicated manufacturing growth was at its highest level in three years.
Its U.S. Manufacturing Purchasing Managers’ Index registered 55.6 in March, up from 55.3 in February. The latest PMI reading indicated the strongest improvement in manufacturing business conditions since March 2015. The average PMI reading over the opening three months of 2018 meanwhile indicated the best quarterly performance since the third quarter of 2014.
Like the ISM gauge, the one from IHS Markit indicates manufacturing is expanding when it is above a level of 50, although it's not expressed as a percentage.
The report showed output levels at manufacturing firms continued to expand strongly in March. Although the rate of growth softened to a four-month low, the pace of expansion remained comfortably above the long- run series average. Panelists commonly reported that the latest rise was driven by firmer client demand.
“Optimism about the year ahead has meanwhile also risen to its highest for three years, generating yet another solid payroll gain and suggesting strong growth momentum will be sustained in the second quarter,” said Chris Williamson, chief business economist at IHS Markit. “Companies cited rising demand at home and abroad plus recent government policy announcements as helping shore up confidence in terms of their future production levels.”
However, Williamson noted that recent tariff announcements by the Trump administration were already reported to have added to inflationary pressures, and have led to the stockpiling of goods expected to rise further in price in coming months.
“Input cost inflation consequently hit the highest since 2012. Increased costs were often passed on to customers, meaning prices charged for goods at the factory gate showed the steepest rise in over four years,” he said.
Construction Spending Edges Higher
A new Commerce Department report on U.S. construction spending showed it increased just 0.1% in February from January’s revised level.
However, the February level of $1.27 trillion was 3% better than the same time in February 2017. During the first two months of the year, construction spending increased 4.4% from the same time a year earlier.
A 0.7% gain in private construction in February from January was outweighed by a 2.1% decline in public construction projects.
Analysts at Econoday noted that despite the overall soft month-over-month performance, there is strength in the homebuilding sector, and building for transportation projects and commercial projects have also improved lately.
Final 2017 GDP Performance Pushed Higher
All of these reports follow one from late last week showing the overall U.S. economy grew more in the final quarter of last year than earlier estimates.
The Commerce Department reported in its third estimate that the nation's gross domestic product (GDP) increased at an annual rate of 2.9% in the last three months of 2017. This compares to its second estimate of 2.5% and third quarter 2017 growth of 3.2%.
According to MarketWatch, this upward revision was due to the biggest increase in consumer spending in three years and higher investment in business inventories.
The U.S. GDP increased 2.3% in 2017 from the year before, compared with an increase of 1.5% in 2016 from 2015.
While the U.S. economy ended 2017 on fairly high note, MarketWatch noted it may have gotten off to a softer start in 2018. Most economists predict the GDP will grow less than 2% in the first quarter due to slower spending by consumers and businesses. The first government estimate for first quarter GDP performance is expected to be released late this month.
More Fleet Management
Kodiak Lines Up Fleets for Driverless Trucking
An agreement for 75 trucks, a new Texas freight lane, and progress on safety validation move Kodiak closer to its planned driverless highway launch.
Read More →
ITS Logistics Settles Religious Harassment Case
The Nevada-based logistics firm agreed to pay more than $396,000 to settle a religious harassment charge involving an employee's Jewish identity.
Read More →
Your Trucks Are Busy. That Doesn’t Mean They’re Winning.
High utilization doesn’t always mean strong margins. Looking beyond the current load can help fleets make better dispatch decisions and get more value from each truck’s time.
Read More →
Why This Trucking Recovery Is Different
Freight demand remains sluggish, but rising costs and tougher enforcement have taken enough capacity out of the market to change the outlook for motor carriers.
Read More →
Platform Science Adds Dispatch and Safety Tools
Four additions to PS Fleet help fleets monitor loads, manage driver coaching, share truck locations and adjust video system settings.
Read More →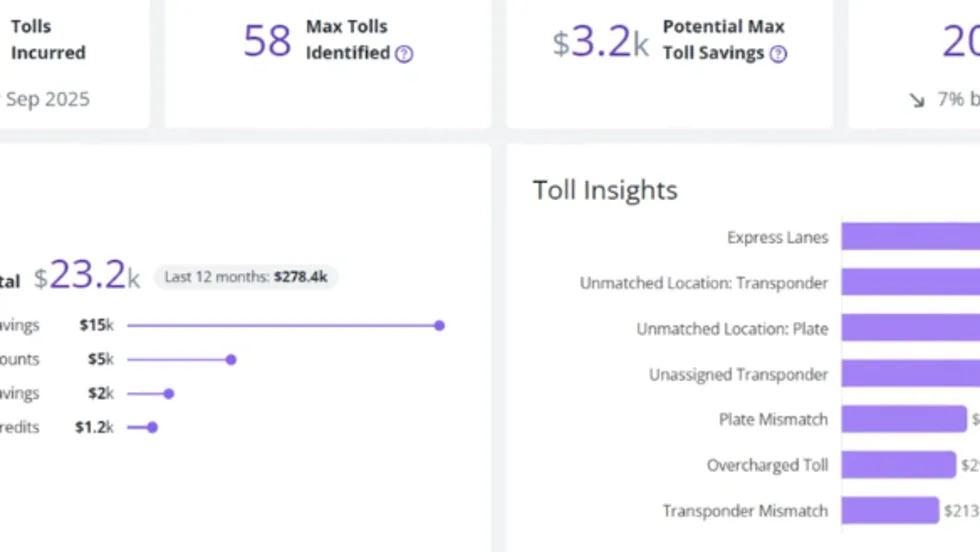
PrePass Intelligence Mines Fleet Bypass, Toll and Safety Data
PrePass Intelligence helps fleets measure bypass savings, flag potential toll overcharges, and spot suspicious transactions by combining data from separate systems.
Read More →
Motive Adds AI Agents for Fleet Operations
New tools automate follow-up on fleet data, from maintenance work orders to driver alerts, with two-way voice conversations planned for later this year.
Read More →
Can You Beat Our Trucking Trivia Challenge?
Test your truck knowledge with 19 trivia questions from Heavy Duty Trucking Exchange. Can you keep up with the fleet pros?
Read More →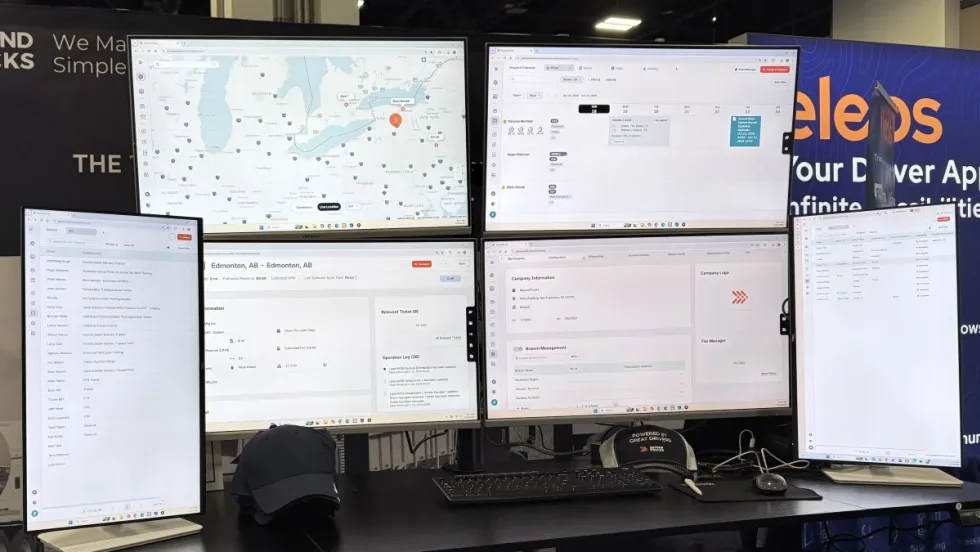
BeyondTrucks Adds Rules Checks to Dispatch
New Compatibility Engine checks driver qualifications, equipment requirements and fleet policies before loads are dispatched.
Read More →
Diesel Prices Hijack Trucking’s Worry List
ATRI’s annual survey finds cautious optimism about freight, but diesel costs, litigation, and insurance continue to squeeze fleets. Drivers have different priorities on several issues.
Read More →